Comptroller reveals multiple deficiencies with accounts receivable and documents administration in the Municipality of Sabana Grande
The Office of the Comptroller of Puerto Rico (OCPR) issued a qualified opinion of the fiscal operations of the Municipality of Sabana Grande. A qualified opinion is issued when the instances of noncompliance, individually or in the aggregate, are significant, but not pervasive.
The Report reveals that the Municipality of Sabana Grande has 645 accounts receivable of patents and excise taxes overdue for $705,105, of which 15% was more than five years overdue. Due to the time elapsed, these accounts could become uncollectible.
The audit of six findings notes multiple deficiencies such as the fact of granting a patent to a taxpayer who owed $37,534 since 2013. This debtor made payments for the calendar years 2017 to 2022, however, the payments were not applied to the debts with the greatest age.
From the examination of the accounts receivable at the Bernice Guerra Polyclinic, it was validated that $211,585 in accounts receivable for ambulance services were not included in the municipalities' accounting software – SIMA. In addition, they also did not record $27,403 in accounts receivable from employees and former employees, and did not bill the medical plans services for $30,645.
In this regard, the Finance director did not adequately supervise the operations and did not look after the best interests of the Municipality. In addition, by not renewing the license of the clinical data and billing registry, ClinNet, the billing work to the medical plans could not continue.
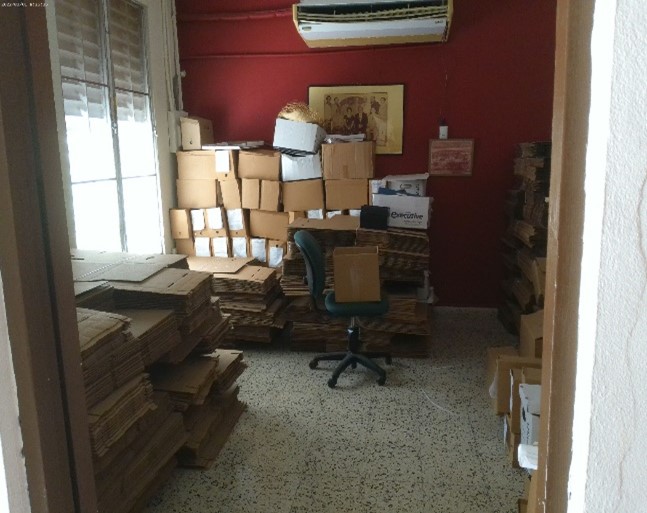
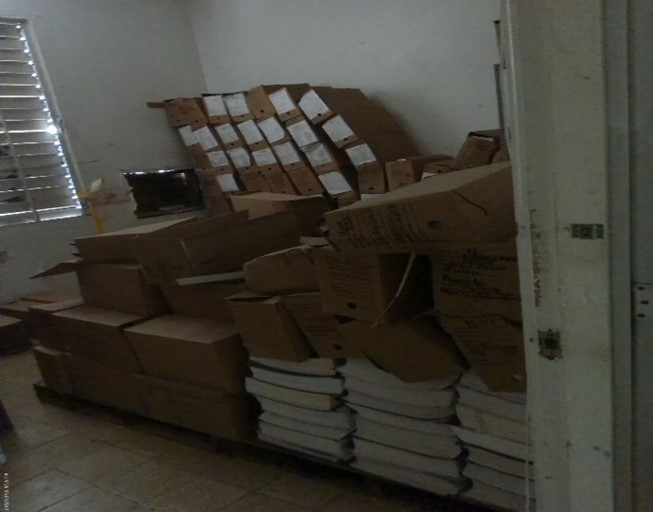
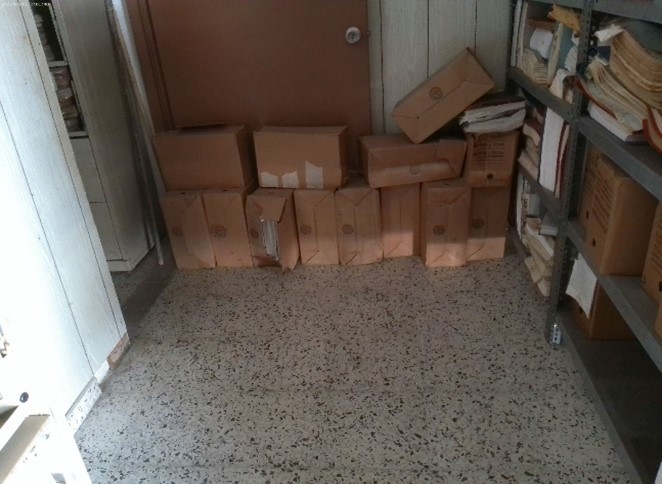
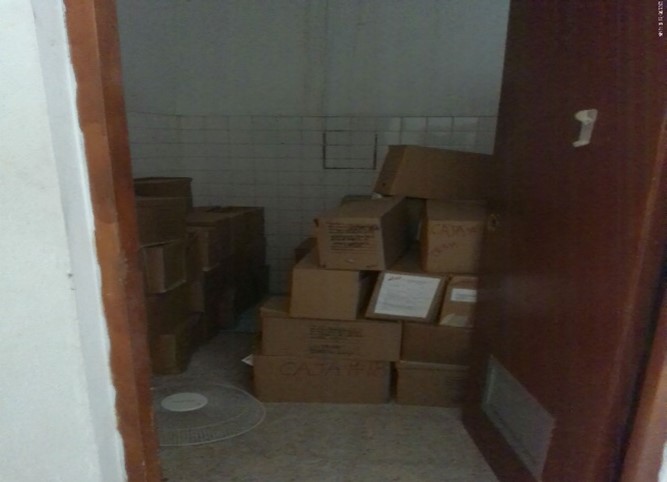
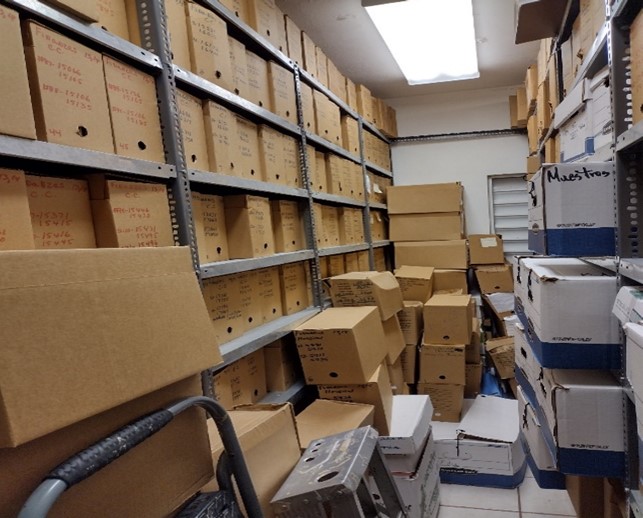
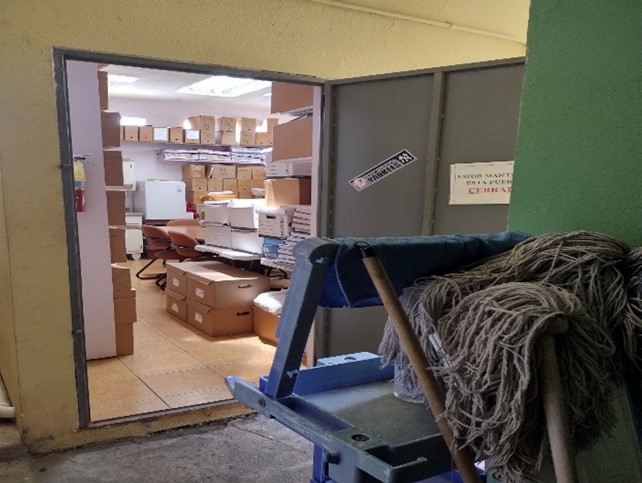
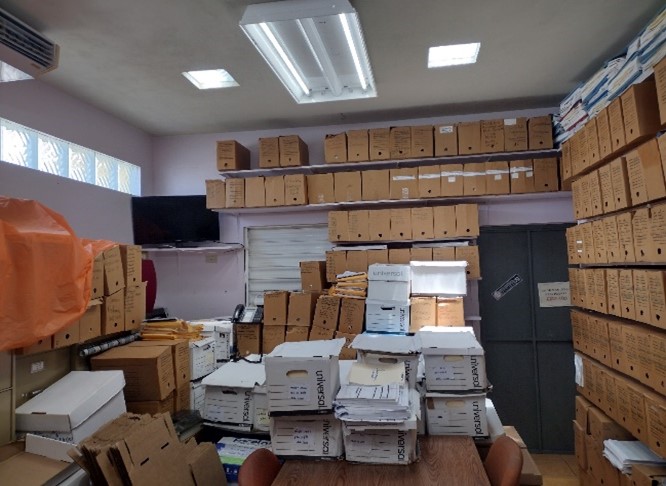
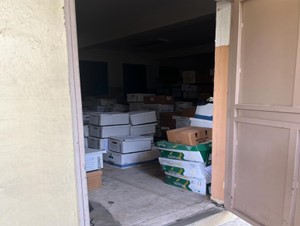
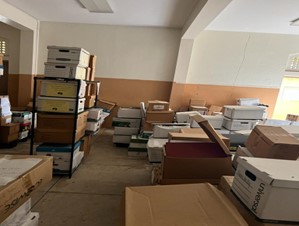
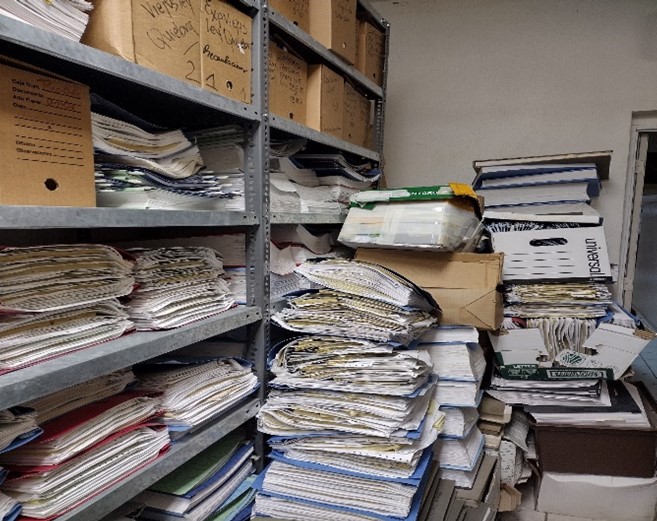
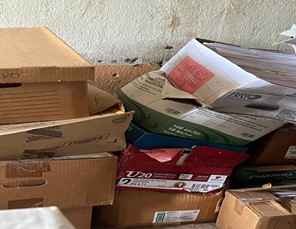
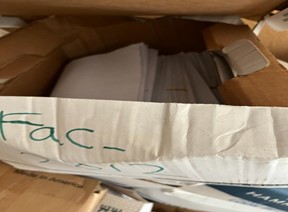
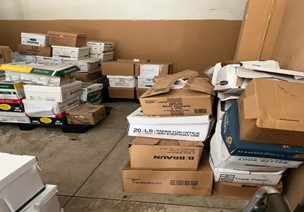
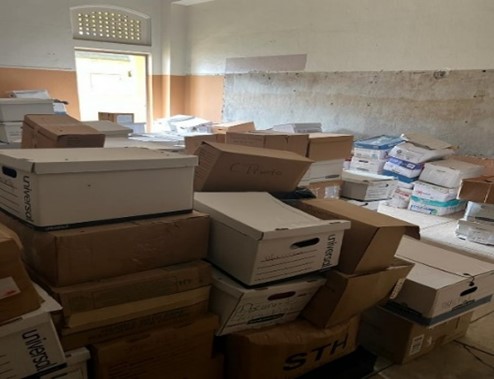
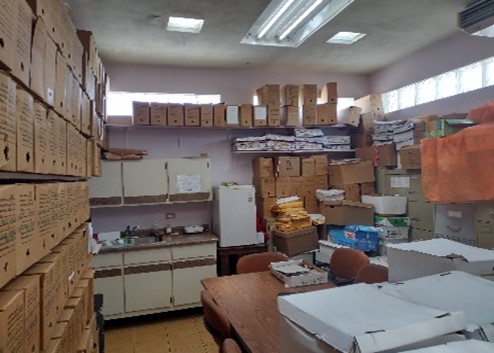
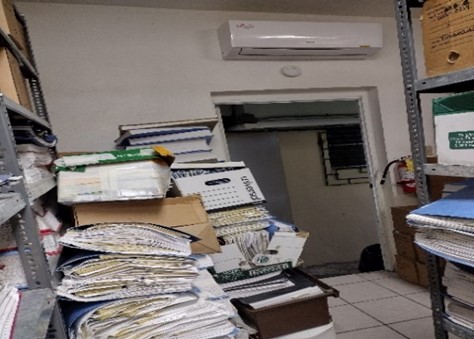
The Municipality does not maintain adequate administration and control of the public documents. For example, they did not prepare the Inventory or the Documents Retention Plan from 2020 to 2022, nor the document disposition lists.
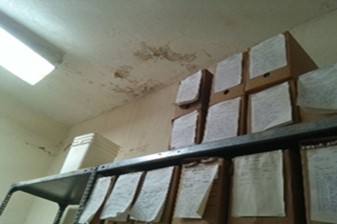
In addition, the archives in the City Hall lacked fire alarm control, the inspection of the extinguishers was from 2014 and they presented humidity stains on the boxes and on the ceiling. In the other three archive areas, unidentified files, cracks in the ceilings and air conditioners that did not work were found.
The auditors identified two special accounts, whose bank reconciliations were reconciled up to three years later. The current regulations provide that the bank accounts must be prepared monthly. As of June 22, 2023, the Municipality maintained 52 bank accounts in a financial institution.
The Report reveals that 40% of the minutes of the Bidding Board were not printed, and 60% of the minutes were not signed by the president of the Board and/or by the secretary of the Board. Of the 183 meetings evaluated, 27 correspond to the former mayor and 82 to the administration of the current mayor.
The Municipality of Sabana Grande sent to the OCPR 65% of the information of the Positions Registry up to 14 months after the date provided by the regulations. This Monthly Report of Payrolls and Positions allows the public to know the payroll expenses and occupied and vacant positions of the Municipality.
The audit indicates that the Municipality lacks procedures on purchases, equipment rentals or services rendered in case of emergencies caused by disasters. The Municipality also had not updated the Purchasing Regulation that dates from 2005.
The Report comments that Sabana Grande had an accumulated deficit of up to 29% of its operational fund in fiscal year 2023. The Mayor and the Legislature must not spend any amount that exceeds the allocations and funds authorized by ordinance or resolution. The Municipality is obligated to include in the budget of the following year the necessary and sufficient resources to respond for the credit of the previous fiscal year.
In addition, the operational budgets of the Municipality from 2020 to 2023 reflected that an average of 41% of the income comes from state allocations. This situation affects fiscal autonomy and causes dependence on the State to ensure operations.
The Municipality's General Fund budget was $8,758,336, $9,021,864, $8,977,349 and $8,462,879, for fiscal years 2020 to 2023, respectively.
The Municipality had prepared its financial statements, which reflected accumulated deficits of $4,978,678, $4,613,958, $3,845,413 and $2,430,874, for fiscal years 2020 to 2023, respectively.
The audit recommends that the director of the Office of Management and Budget ensure that the Municipality of Sabana Grande complies with the Corrective Action Plan of the Office of the Comptroller of Puerto Rico.
This report covers the period from January 1, 2020 to June 30, 2023.
The Audit Report OC-25-19 can be obtained on our website: www.ocpr.gov.pr.





Some documents on this page are saved in PDF format.
To view these documents, you must have the following free program installed.







